AI Doubts, Peace Doubts
The recent inverse relationship between equities and oil was on full display yesterday. Global stocks, led by the tech-heavy Nasdaq Composite Index, weakened considerably. Fears about the sustainability of the AI craze are ominously mounting. The trigger for yesterday’s rout was Meta, as the Facebook owner warned of the need to borrow hundreds of billions of dollars in the coming years as the AI race intensifies. To add insult to injury, weekly US jobless claims fell to a 57-year low, bearing witness to a solid labour market that will not stand in the way of further rate hikes should persistent inflationary pressures warrant them.
The relentless strength in oil prices points to elevated consumer prices ahead. The utter lack of progress towards a truce or armistice in either Ukraine or Iran continues to weigh on and drive market sentiment. Brent settled at its highest level since early May, while Heating Oil gained 3.5%. Russian peace talks are cheap, but the ongoing exchange of drone attacks between Moscow and Kyiv keeps the conflict very real. Strikes on ships in the Strait of Hormuz will inevitably affect oil exports, while Aramco’s order to evacuate its headquarters in Dhahran is a sure-fire sign of the antagonism between the Kingdom and the Houthi militant group. Topping off this explosively bullish oil cocktail was the halt in production at two of Libya’s oil fields due to a pipeline valve being shut. There is neither an intention nor any hope of reducing geopolitical tension and the related risk.
US Inventory Backdrop Remains Price Supportive
You do not hear the expressions ‘critically low’ or ‘operational tolerance’ very often these days. Only a few months ago, experts and analysts were warning, unconditionally and justifiably, that oil inventories, whether global or regional, commercial or strategic, had come within a whisker of falling so low that no further drawdown would be feasible. It feels as though something has changed, and that stockpiles, despite volatile and sometimes vicious market conditions, have started to stabilise, even if they are not yet at comfortable levels. Well, this feeling is excessive zeal.
The monthly reports from the triumvirate of EIA/OPEC/IEA are probably not the most reliable sources for our immediate purposes, for two reasons: they do not provide particularly high-frequency data, and their prognoses diverge irreconcilably. Taking a deep dive into the EIA’s latest Petroleum Status Report might be a more useful approach, as it is published weekly and, although it provides only regular snapshots of the US oil landscape, its findings can be extrapolated to the global market, or at least to the OECD. After all, US industrial stocks account for around 45% of OECD inventories; consequently, any change or fluctuation in them will, by extension, have a profound impact on stockpiles in the developed world.
Commercial oil stocks are historically depleted. Last week, they fell by 8.5 million bbls, leaving them 69 million bbls (5.4%) below last year’s level and 35 million bbls (2.8%) below the long-term seasonal average. At 1.215 billion bbls, they are a mere 18 million bbls above the year’s low, recorded at the beginning of July, which was the lowest since July 2022. A source of encouragement is the EIA’s Short-Term Energy Outlook, which envisages commercial stocks remaining stable for the rest of 2026 before gradually building next year, ending 2027 at 1.34 billion bbls. However, as has been discussed frequently on these pages, these estimates are based on the assumption that the Middle East conflict will come to an end in the foreseeable future. If it does not, forecasts will have to be revised, and a small change in assumptions will lead to a major change in conclusions.
As for crude oil, it is worth starting with strategic stocks. As a major contributor to the IEA’s SPR release programme, covering 400 million bbls and possibly an additional 100 million bbls, the four salt caverns in Texas and Louisiana now hold a mere 283 million bbls of crude oil, down from 415 million bbls just before the Iranian conflict broke out. Meanwhile, the decade’s high of 656 million bbls, recorded in 2020, has completely disappeared in the rearview mirror. The annual decline of 10 million bbls in crude oil inventories, which has taken them 11 million bbls below the five-year average, reflects rising, albeit fluctuating, demand for US crude oil. The world’s largest producer has been sending an average of 4.26 mbpd of its crude oil overseas, 400,000 bpd more than the 2025 mean. The repercussion of the hostilities in the Middle East is conspicuous.
Of the two major refined product groups, gasoline is in a somewhat less uncomfortable position. Its annual deficit is ‘only’ 5.2%, compared with 9.7% for distillates. The five-year average is 3.9% above current gasoline stocks, while the corresponding shortfall for diesel/distillates is 5.8%, despite last week’s stock build. Refiners have been pumping as hard as they can, but the astronomical rise in product exports, which have averaged 1.7 mbpd above the comparable period of 2025 on a net basis March-to-date, has kept domestic inventories at severely distressed levels. This surge is purely a function of the race to replace lost Middle Eastern and Russian volumes, much to the chagrin, but hardly to the surprise, of the US Administration. The impact on prices is there for everyone to see.
Looking at the state of US oil stocks from a different angle produces the same result. Wednesday’s Weekly Petroleum Status Report suggests that US commercial oil inventories would cover 57 days of domestic consumption. For distillates, the figure is 28 days, and for gasoline, 23 days. Needless, perhaps, but useful to point out that these figures are considerably lower than before the conflict or a year ago. In the same order, the shortfalls are five and six days for total commercial oil stocks, five and two days for distillates, and seven and two days for gasoline. Once the conflicts are settled amicably, the change will be discernible. For now, however, if one accepts that the backdrop of US oil inventories is indicative of the global oil balance, it would be premature to expect the ursine community to emerge from hibernation.
Overnight Pricing
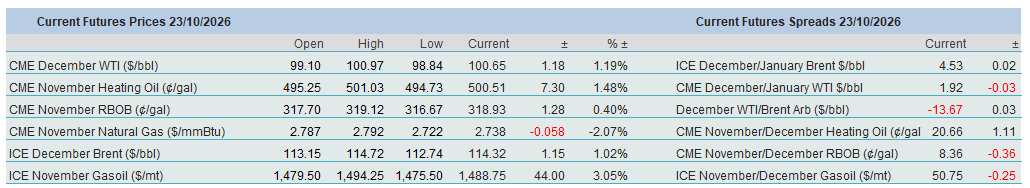
23 Oct 2026
